Singapore’s shift toward cashless payments did not start with online gaming. It grew through everyday activities such as paying merchants, transferring money to friends, shopping online and managing bills from mobile banking apps.
Systems such as FAST, PayNow and SGQR reduced many of the steps once associated with electronic transfers. Instead of entering full bank details, users now complete many payments through a mobile number, an identifier or a QR code.
PayNow, launched for participating banks on 10 July 2017, lets users transfer Singapore dollars through FAST without knowing the recipient’s bank account number. The service operates around the clock.
These experiences have also influenced what Singapore players expect from payment systems. Speed matters, but the bigger change involves fewer steps, easier mobile access and clearer transaction status.
Explore More: PayNow Casino Singapore
Quick Answer
Cashless payments have become more relevant to Singapore players because they match payment habits already established outside gaming. Mobile banking, PayNow and QR payments make it easier to initiate transfers, confirm recipient details and check transaction records without handling cash or manually entering long account numbers.
The important distinction is between payment-network speed and platform-processing speed. A bank transfer might complete almost instantly while the receiving platform still needs to identify, verify and credit the transaction. Understanding both stages gives players a more accurate view of what a “fast payment” means.
How Singapore Moved Toward Cashless Payments
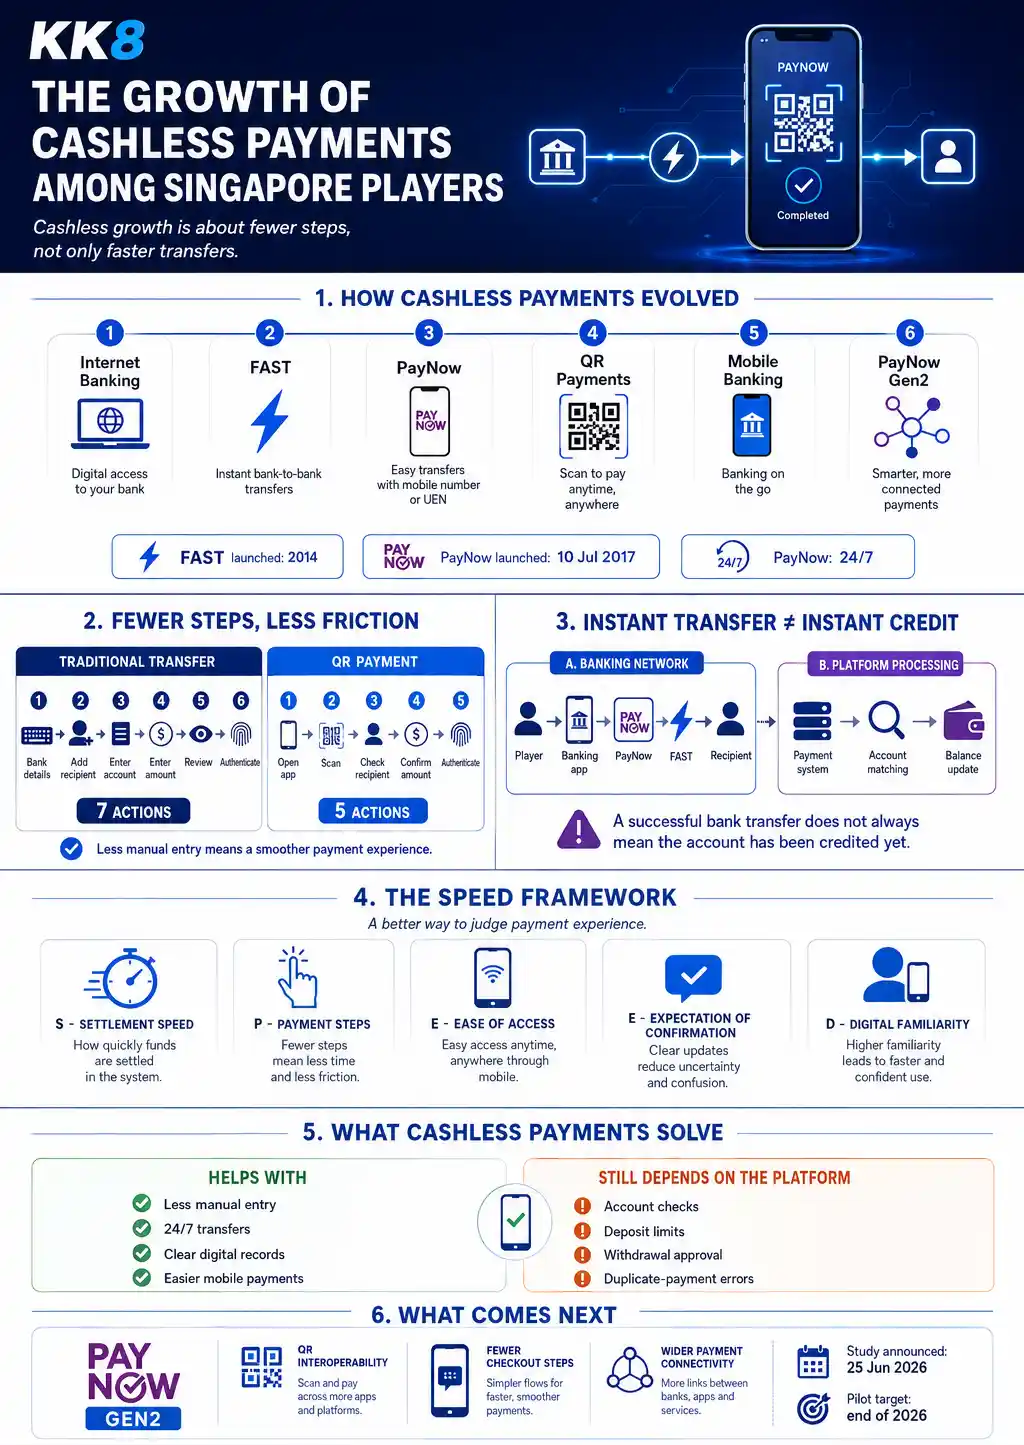
Singapore’s cashless transition developed over several stages. Each stage reduced a different form of payment friction.
| Payment development | What changed for users |
| Internet banking | Transfers moved from branches and ATMs to online banking |
| FAST | Singapore-dollar bank transfers became almost immediate |
| PayNow | Users no longer needed full account details for many transfers |
| PayNow QR and SGQR | Scanning replaced more manual payment entry |
| Mobile banking | Payments, records and authentication moved onto one device |
| PayNow Gen2 | Planned enhancements target fewer checkout steps and wider interoperability |
FAST, or Fast And Secure Transfers, launched in March 2014. It allows customers at participating financial institutions to transfer Singapore-dollar funds between accounts almost instantly. PayNow later built a simpler addressing layer on top of FAST.
That distinction matters. FAST is the transfer infrastructure. PayNow provides a simpler way to identify who receives the money.
PayNow Reduced the Need for Account Details
Traditional transfers often require the recipient’s bank name and account number. PayNow changes the process.
Eligible users transfer funds through identifiers such as a mobile number, NRIC/FIN or Virtual Payment Address. Businesses also receive payments through PayNow Corporate using their UEN. For users, this reduces input rather than merely reducing processing time.
Read more: How PayNow Transfers Work in Singapore
QR Payments Reduced Payment Steps Further
QR payments change the payment journey again. A simplified traditional transfer might involve:
Find bank details → Add recipient → Enter account information → Enter amount → Review → Authenticate → Confirm
A QR-based journey might look more like:
Open banking app → Scan → Check recipient → Confirm amount → Authenticate
The exact steps vary between banks and services, but the direction is clear. Payment design has shifted toward reducing manual entry. This helps explain why cashless payment growth should not be measured through transaction speed alone.
Why Cashless Payments Appeal to Singapore Players
Players experience the same payment friction as other online consumers. They need to choose a payment method, complete a transaction and confirm whether it succeeded.
Several features make modern cashless systems more practical.
Fewer Manual Steps
Every extra field creates another opportunity for a typing error. QR payments and registered PayNow identifiers reduce the amount of information users need to enter manually.
Fewer steps also make mobile transactions easier because users spend less time switching between pages or copying banking details.
24/7 Payment Access
PayNow is available 24 hours a day, 365 days a year. This has changed the meaning of a bank transfer for many Singapore users. A bank payment no longer automatically means waiting for a branch, banking day or manual processing window before the underlying transfer begins.
Clearer Transaction Status
Modern banking apps normally display transaction status after a transfer.
This gives users a record showing:
- Amount
- Recipient
- Date and time
- Transaction reference
- Transfer status
These records help when a receiving platform does not update an account immediately.
Mobile-First Payment Management
The same phone often handles payment initiation, authentication, confirmation and transaction history. This consolidation matters because convenience comes from the full payment journey, not one technical feature.
Payment Speed Is No Longer the Only Measure
Articles comparing payment methods often focus on one question:
Which method is fastest?
A better question is:
How much effort does the user need to complete and verify the payment?
Consider two methods taking roughly the same amount of time.
Method A requires eight manual actions.
Method B requires four.
Users often perceive Method B as the smoother payment experience even if the final settlement difference is small.
This introduces a useful concept: payment friction.
The SPEED Framework for Cashless Payments
A payment experience can be assessed through five factors, which together help evaluate how smooth and efficient a transaction feels. These factors provide a structured way to compare different payment methods beyond just speed.
| Factor | What to examine |
| Settlement Speed | How quickly funds move through the payment network |
| Payment Steps | How many actions the user completes |
| Ease of Access | Whether the method works easily through familiar devices and apps |
| Expectation of Confirmation | How clearly the transaction status appears |
| Digital Familiarity | How familiar users already are with the payment method |
This SPEED framework is an editorial model for comparing user experience. It is not an official banking-industry measurement. Its value lies in looking beyond a simple “instant versus slow” comparison.
A payment method might settle quickly but still create friction through complicated forms, unclear instructions or additional manual verification.
Read more: What Makes Fast Casino Payments Important Today?
Instant Transfer Does Not Always Mean Instant Account Credit
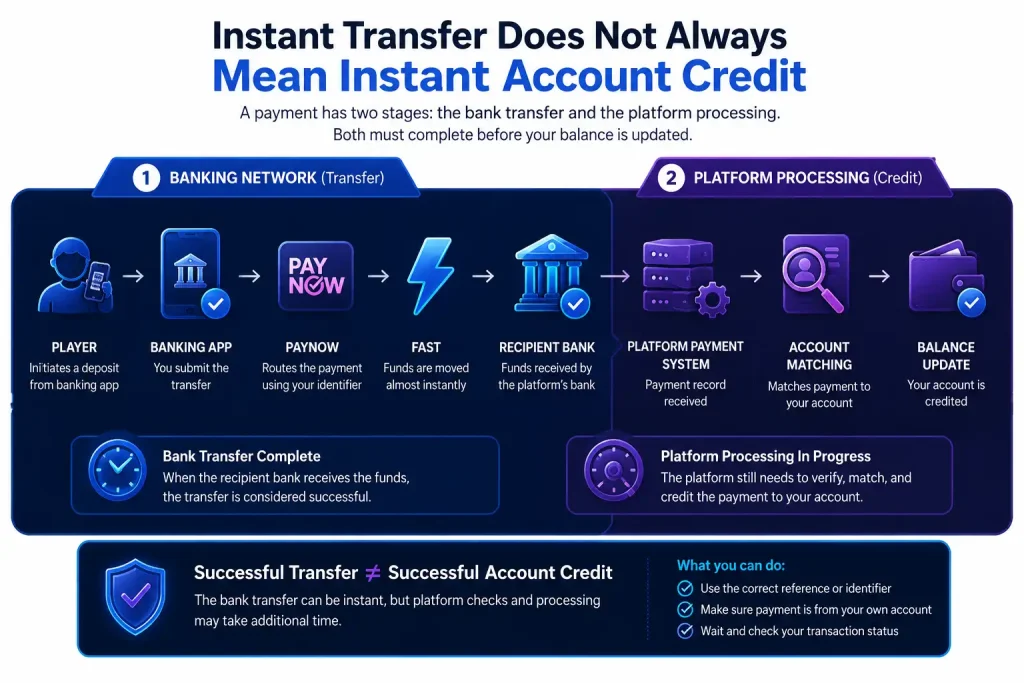
This is one of the most important distinctions for players. A typical PayNow-related deposit journey looks like this:
Player → Banking app → PayNow → FAST → Recipient → Platform payment system → Account matching → Balance update
The bank transfer and the receiving platform are different parts of the process.
A successful PayNow transfer means the banking stage reached the recipient. It does not automatically prove the receiving platform has completed its own processing.
Singapore Pools provides a useful regulated local example. Its PayNow deposit guidance states a deposit might remain pending or be rejected due to an account-status check, deposit-limit issue, duplicate QR transaction or use of an unsupported third-party, joint or corporate account.
This shows why users should avoid treating “money left my bank” and “my account has been credited” as the same event.
Read more: Why Is My PayNow Deposit Not Showing?
How Cashless Payments Changed the Online Casino Deposit Experience
Cashless systems have reduced several pain points associated with older transfer processes.
Users increasingly expect:
- Mobile payment initiation
- Fewer manual fields
- Recipient verification before confirmation
- Immediate bank-side transaction status
- 24/7 availability
- Searchable digital transaction records
Singapore Pools offers a local example of a QR-based deposit flow. Its official process involves generating a PayNow QR code, scanning it through a participating banking app and completing the transaction within the QR validity period.
The important lesson is not the specific online gaming platform. It is how familiar consumer payment behaviour has entered account-funding journeys.
Related guides:
How to Deposit Using PayNow at an Online Casino
Instant PayNow Deposits vs Manual Transfers
Cashless Payments Also Changed Withdrawal Expectations
Deposit speed is only half of the payment experience. When users become familiar with near-real-time transfers, they start paying closer attention to how quickly money moves in the opposite direction.
A withdrawal usually has more stages:
Withdrawal request → Platform checks → Approval → Payment instruction → Banking network → Recipient account
This explains why a platform supporting a fast payment rail might still have a slower withdrawal process. The delay might occur before the payment network receives the instruction.
This distinction is important when comparing withdrawal claims. “PayNow withdrawal” describes the payment route, not necessarily the full processing time.
Related guides:
How to Withdraw Casino Winnings with PayNow
Why Is My PayNow Withdrawal Delayed?
What Cashless Payments Solve, and What They Do Not
Cashless payments improve several parts of the transaction experience, but they do not remove every source of delay or error.
| Issue | Does cashless payment help? | Explanation |
| Manual bank-account entry | Yes | QR codes and registered identifiers reduce manual input |
| 24/7 transfer initiation | Yes | PayNow operates around the clock |
| Transaction records | Yes | Banking apps provide digital payment histories |
| Wrong-recipient risk | Not completely | Users still need to verify recipient details |
| Platform account checks | No | Receiving platforms set their own checks |
| Deposit limits | No | Limits still apply |
| Withdrawal approval | No | The platform normally handles approval before payout |
| Account verification | No | Identity and account checks remain separate processes |
| Duplicate payment errors | No | Users still need to follow the correct payment process |
The Association of Banks in Singapore advises users to check the recipient’s displayed name before confirming a PayNow transfer.
What PayNow Gen2 Says About the Next Stage of Cashless Payments
Singapore’s payment system continues to develop, with ongoing improvements to speed, interoperability and user experience across services like PayNow, FAST and QR-based payments.
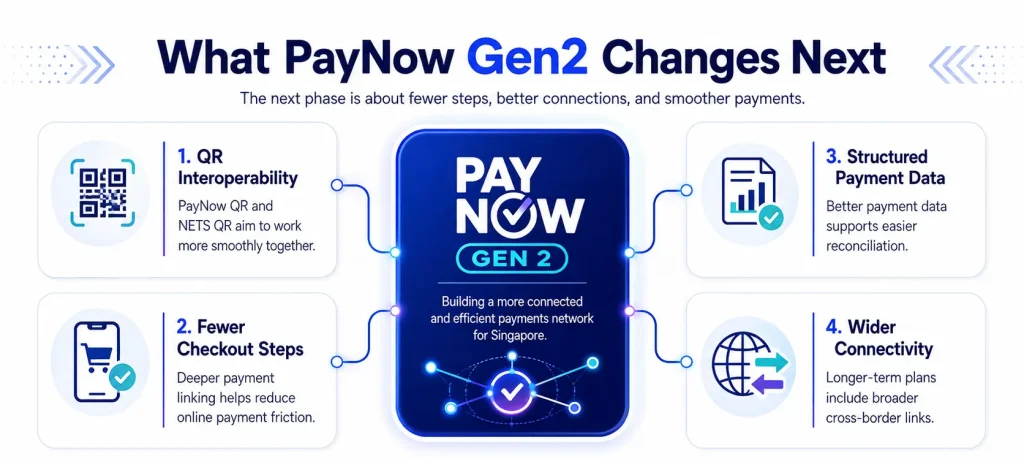
On 25 June 2026, the Monetary Authority of Singapore and the Association of Banks in Singapore announced a PayNow Generation 2 study focused on four areas of enhancement.
One proposal involves interoperability between PayNow QR and NETS QR. This would let consumers scan and pay merchants across the two payment schemes more easily. A pilot is targeted for the end of 2026.
Another area focuses on improving online checkout through deeper linking within PayNow QR flows. The stated goal includes reducing payment steps. Longer-term areas include request-to-pay functions, structured payment data for automated reconciliation and broader cross-border connectivity.
These developments support a wider trend: the next phase of digital payments is not only about moving money faster. It is also about reducing friction around the transfer.
Related guides:
How Digital Payments Changed Online Gambling in Singapore
A Better Way to Measure Cashless Payment Progress
The growth of cashless payments should not be judged through transaction volume alone. For users, progress also appears through practical changes:
- More manual entry → Less manual entry
- Account numbers → Registered identifiers and QR codes
- Banking-hour thinking → 24/7 transfers
- Transfer completed → Clear digital status
- Separate banking tasks → Mobile-first payment management
- Long checkout journeys → Fewer payment steps
For Singapore online casino players, these wider changes matter because payment expectations do not develop inside gaming platforms alone. They come from everyday experiences with banks, shops, online services and person-to-person transfers.
A player accustomed to scanning a QR code and seeing a payment status within seconds is likely to notice unnecessary payment friction elsewhere. That is the larger story behind cashless payment growth.
Frequently Asked Questions
Why are cashless payments growing in Singapore?
Cashless payments reduce the need for physical cash and manual banking information. Systems such as FAST, PayNow and QR payments also support mobile and round-the-clock transactions. PayNow itself operates 24/7 and sends funds through FAST.
Is PayNow a cashless payment method?
Yes. PayNow is an electronic funds-transfer service. It lets participating users send and receive Singapore dollars through FAST using registered identifiers rather than relying solely on bank account numbers.
What is the difference between FAST and PayNow?
FAST is Singapore’s electronic funds-transfer infrastructure for near-immediate Singapore-dollar transfers between participating institutions. PayNow runs through FAST and makes transfers easier by letting users identify recipients through registered proxies such as mobile numbers or NRIC/FIN.
Does an instant PayNow transfer mean an instant deposit?
Not always. The banking transfer and the receiving platform’s account-crediting process are separate stages. A recipient platform might still perform account matching, limit checks or other processing after funds arrive. Singapore Pools documents several cases where a PayNow deposit might remain pending or be rejected despite the payment process being initiated.
What is PayNow Gen2?
PayNow Gen2 is a 2026 MAS and ABS initiative examining improvements to Singapore’s instant-payment infrastructure. Areas under study include PayNow-NETS QR interoperability, fewer online checkout steps and longer-term improvements such as automated reconciliation and wider cross-border payment functions.
Sources
Association of Banks in Singapore, PayNow Singapore and PayNow Fact Sheet.
Singapore Pools, Singapore Pools Account Deposit Through PayNow Guide.
Gambling Regulatory Authority of Singapore, Licences for Gambling Operators